The metrics
Available onDeveloper
Twelve tiles sit above the feasibility. Most developers watch three of them. The rest matter on the day you sit in front of a lender.
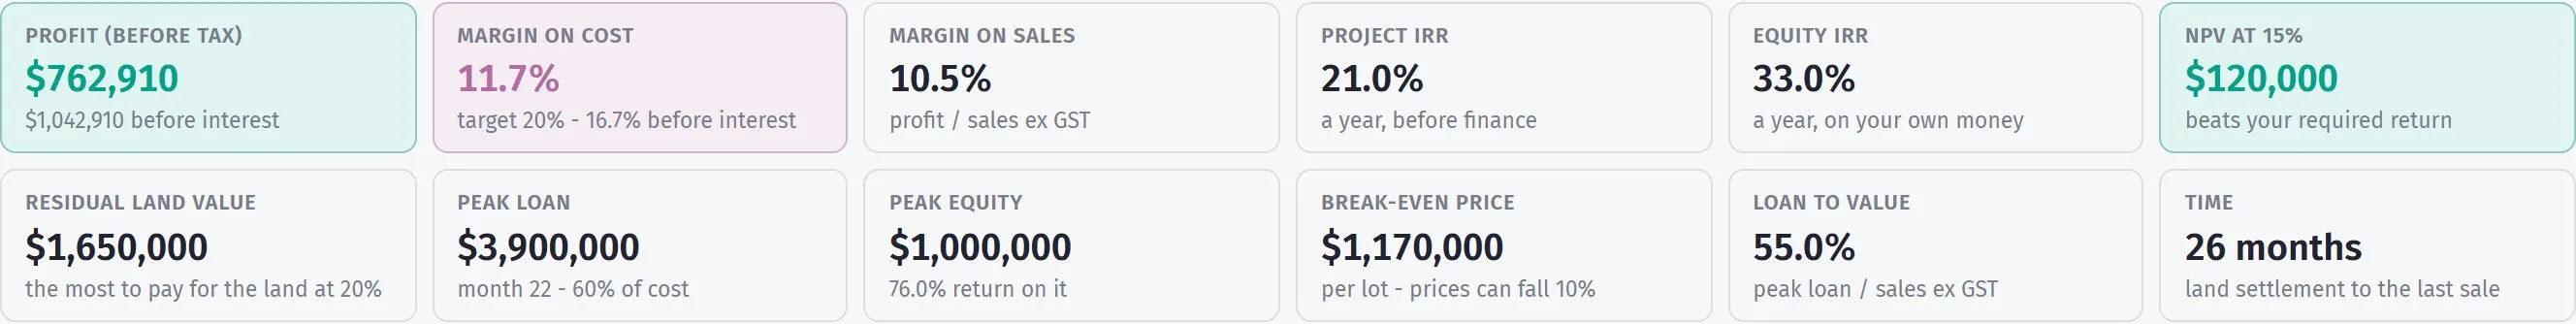
Twelve tiles. The margin tile carries your target, so a project below it shows pink.
The three you will actually watch
Section titled “The three you will actually watch”Profit (before tax)
Section titled “Profit (before tax)”Everything you sell, less GST and selling costs, less every cost including the interest. Before tax — what you owe the ATO afterwards depends on your structure, and SmarteBuild does not know it.
Margin on cost
Section titled “Margin on cost”Profit ÷ total development cost. This is the number banks ask for, and most want 15–20% or better before they will lend. The badge on the developments list is set against the target you choose.
The tile shows your target beside the figure, and the margin before interest underneath, so you can see how much of the gap is the bank’s.
A thin margin is not only a small profit. It is a project with no room for a wet winter.
Residual land value
Section titled “Residual land value”The most you can pay for the land and still hit your target margin. It is the answer to “should I buy this site?”, worked out backwards from the margin you asked for.
If the agent wants more than this number, the site does not work at your target — not at that price, not without changing the build or the sale prices.
The time-based ones
Section titled “The time-based ones”These are the reason the feasibility asks when, not just how much.
NPV at 15%
Section titled “NPV at 15%”The tile carries your own discount rate in its name, so it reads NPV at 15% if that is what you set. It is your profit in today’s dollars at that rate — your required return, say 15% a year. Above zero means the project beats that return. Below zero means your money would do better elsewhere, even if the profit looks healthy.
Project IRR
Section titled “Project IRR”The yearly return the whole project earns on all the money in it, before finance. Compare it with other sites.
Equity IRR
Section titled “Equity IRR”The yearly return on your own cash, after the bank has been paid its interest. This is what you personally earn, and it is normally higher than the project IRR — that is what borrowing does, in both directions.
The ones the bank asks about
Section titled “The ones the bank asks about”Peak loan
Section titled “Peak loan”The most the bank is owed at any single month, with the month it happens in and what share of the total cost it is. Compare it with your loan limit. A feasibility that works but peaks above the facility is not fundable.
Peak equity
Section titled “Peak equity”The most of your own cash tied up at once, and underneath it the return you make on that cash. Two projects with the same profit can need very different amounts of your money, and this is where that shows.
Loan to value
Section titled “Loan to value”Peak loan against the value behind it. Lenders have their own ceiling, usually quoted as LVR.
Break-even price
Section titled “Break-even price”The lowest average price per lot before the project stops making money, with how far prices could fall before you reach it. Hold it against what is actually selling nearby — if there is no room between the two, the project depends on the market not moving.
The rest
Section titled “The rest”Margin on sales
Section titled “Margin on sales”Profit ÷ net sales. Another way of saying the same thing as margin on cost, and the one some lenders prefer.
Land settlement to the last sale settling. It drives the interest bill and it is the figure developers most often underestimate.
Reading them together
Section titled “Reading them together”A site is worth buying when all four of these hold:
- Margin on cost is at or above your target
- Residual land value is at or above the asking price
- Peak loan sits inside a facility you can get
- Break-even price leaves room below what is selling nearby
Any one of them failing is a reason to walk, renegotiate, or change what you are building.
With more than one scenario, Compare puts these same measures side by side and marks the best in each row — see Comparing scenarios.
Then run the what-if grid before you commit — because the four above are all true on the day you type them, and construction takes two years.